Thursday, January 07, 2016

H2 CY15 - Oh! The Humanities


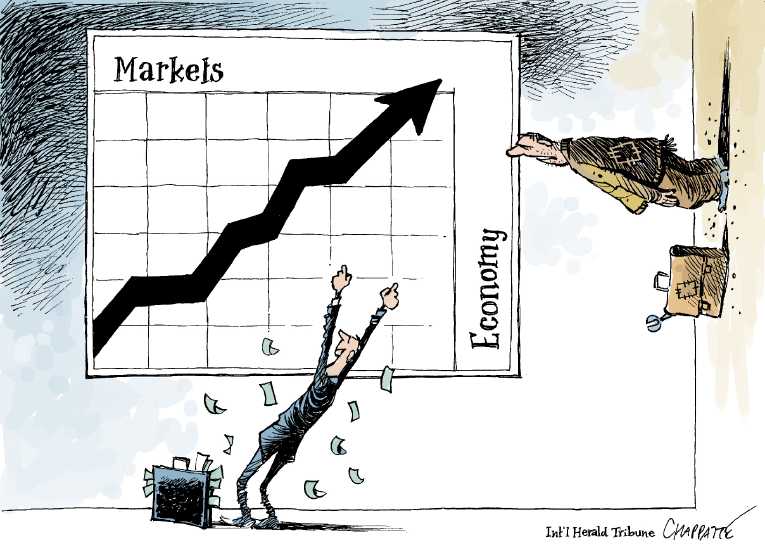
Same story repeating (link) - lots of talks, too much politics, and sadly nothing getting done. Looks like broadcasting such noisy frightful bureaucratic drama on the TV is taking away our mental bandwidth/higher purposes from our lives and society. Purposes like invention, progress, healthcare, basic living rights, etc etc are strangely not visible. Unequal economic distribution, leading to flow of people towards metros is leading to stress, population imbalances, corruption, anxiety, pollution - it looks like a basic fabric of cities is destroyed - Delhi is full of dust and traffic and has become gas chamber, with possibly worst air quality - link. Looks like it will lead to public health epidemic sooner or later. 

Insecurity and unequal opportunity is pretty prevalent today. Unequalness in society is caused by corruption, which inturn is caused by demanding/consuming/hoarding more than one could consume in its lifetime - typical human condition. And it stems possibly from all sort of personal feelings of inadequacies/insecurities/incompleteness/fear. Eckhart Tolle has written/said well about this. Feelings of inadequacies, leads one to accumulate more and more, and consume more and more, giving fuel to commercial entities to exploit our biases. Munger understood this quite early in his life when he quoted - I wanted to get filthy rich like Warren not because I wanted ferraris, but because I desperately wanted to get independent. People misjudge the balance between utility of money (aka personal freedom to pursue one's passions) VS ego-satisfying consumption fueled by money. One is inward virtue, other is external embellishment. [[[[[[["Personal incompleteness" was a topic of great interest to me in last few years, and I was glad to work with few schools in last 2 years - you may see this Project Flourish files here. (and for a hilarious take, see BigBangTheory's Sheldon Cooper's own feelings of incompleteness, leading him unsatisfied and anxious)]]]]]]]

Commercial entities have always flouted our inadequacies/wants and the laws-of-nature with impunity. I am glad about a new wave which has sweeped Indian fmcg sector - Baba ramdev's pitanjali is giving tough fight to incumbent evergreen fmcg players with assumed-to-be permanent indestructible moats. I think the market here was ripe for "somewhat seemingly" honest/organic entity to enter and fight against for-profit-at-any-cost entities. Such entities don't realise that the cost of selling product is not just raw-material/operating costs, but also invisible costs like long term degradation of public health/environment. Things like cokes, snacks, or financial products (CDOs etc) of the worlds may do well for a period, but sooner or later they will come crashing down as a set of public will awaken to their mis-utility. Would be glad if ramdev's or some other organic movement works rationally and succeeds here. 

Rotten Picks 

There aren't many new insights presently. Its difficult to find amalgamation of good management, good business, and right valuations and industry tailwinds at the same time. What amuses me is the constant flow of new picks/gems on the channels and investor meets. Not many talk about old picks where they would like to still buy more and more upwards - as if companies in the pocket start to stink and old ideas begin to rot like vegetables :))..... Unlike food, in investing, one needs to relish rotten picks more than fresh picks. 

There is always a no 4, no 5 and so on, in list of possible opportunities. But they are always compared against no1 and no2. The investing process may look inactive to a novices, but effort is always ON in comparing things at multiple levels. As Jason Zweig says - 99.5% of the time the right thing for people to do is nothing.

We are in good company. 


Monday, July 13, 2015

H1 CY15 - In Thermals


The hawks are making lazy circles as they are in the uplifting convection thermals. 

The FMCG player had seen a radical shift in the power equation in last few months. Few more competitors died. Many refused to participate in crop buying, as the prices fell down and overleveraged traders exited. Lower prices, and higher volumes, is good news. The company was able to grow its dominance - both at the retail end, by expanding network, and at procurement end, by procuring more and by being a ready buyer. Goodwill in community has also increased. 


The wind energy sector is also facing tailwinds. Govt's concessions are helping the industry. But the rest of infra capex is still languishing. The hopes of industry are kicked down the timeline - from end-of-fy15 to H2-of-fy16 to now, maybe-fy17. Overall, volumes are slowing in many industries and we will see negative surprises. The hope-bubble is punchering as industries arn’t seeing much kickstarting on the ground. 


SEBs (state electricity boards) position hasn’t improved as expected. The new government claims that the 2012 FRP (Financial restructuring package) has failed. The losses of SEBs have grown. States like Rajasthan have again approached banks for another loan restructuring. Many guys have not increased power rates as promised in FRP. Without strong political will, conditions in power-distribution are very poor and slow. 

The exuberance of last few months OND & JFM has come down in many sectors.

Good things – India is still being considered as better off in the indebted world. The crude, commodities and mass-market are on our side. And the Indian retail investor is waking up. The capital flows from the Indian retail have jumped sharply, and this looks like to be a year with highest retail participation coming up. 

General et al - Overall, the general environ looks very chaotic today. Govt infights, regulatory indecisions, scams, pollutions, rising population in few metros, adulteration, lawlessness looks common in public affairs. Hats off to the entreprenuers who are still growing in such environs. Hope things smoothen.  


Monday, January 12, 2015

H2 CY14 - Sexy Sirens


General Economy

Lots of marketing is being done by Government to attract investors. Modi is playing relentless tireless cheerleader for India - a true capitalist PM and seems to be putting our best foot forward. Some ambitious projects are being promoted by Government– like the 1 lac MW solar project. For more, check this jazzy presentation by Government – 200 days of power minister’s achievements. Solar is aggressively being pushed and made mandatory for buildings in Haryana. With such initiatives, if implemented, things look good for India.

Oil downfall is another good news for India, as well as for other consuming countries. With oil reaching $50, Indians couldnt have asked for more. Although not passed to consumer, it is still benefiting government to manage the deficit. 

At same time, the fall in soft and hard commodities will reduce incomes for many players, esp. farmers. Rural economy is facing decline as observed by few farmers. The prices of many crops – cotton, rice, wheat, sugar, maize, etc - this season are very low. Even the source of easy money for farmers , viz.  the land sale – is on decline, as no more aggressive land buying is done by Industry or real estate developers.  Overall reduction in farmers' income is visible in decline in agricultural equipments/tractor sale. This doesnt bode well. 

Hope, the dope!

A part of market, sectors like consumption, which were expensive last year, have become psychotic this year. Seems like desperate money/newbies facing deprival super-reaction are chasing and buying in panic. Few companies have shown ZERO growth over past 6 years - zero, nil, nada, zilch!!! - and currently hyped up to justify 60x pe!! Another one, sells at 70x pe, 12x sales! Pied Pipers are playing and rats are high on opium.

Its easy to digress from one's strategy at such times, and get swayed by sexy sirens. The landscape look easy, but it is actually full of landmines. 

YOU as The Chief Manager

The question often arises, what if market tanks down from this level. Secondly, if it falls, do we see absolute crash like 1929?

My take is 1929 kind of situations are averted lately by easy money from the Feds. It has set up a entitlement assumption amongst fund managers that Government will protect the economy/markets no matter what. This is what we saw in last credit crises.  

So, if not an absolute blowout, how do we manage minor setbacks? AND at the same time, how do we think about the scenario where the market goes in opposite direction and becomes fairytale bull runs for 2/3/5 years? My answer is by becoming your own prudent asset allocator.

Time again, we have seen that assets, no matter what, over time, fetch higher valuations provided managements don’t swindle. There would be many buses for each bus missed, but the ticket price every year would escalate. Buffett was right when he said that compounding should start as early as possible – and asset acquisition should be done aggressively early on. 

It makes sense to take consistent additional exposure in assets, with inflows from earning income (or dividends, or insurance float/debt as in case of Buffett).  Managing fixed allocation, with some idle cash on balance sheet is not a great strategy for personal allocations. Rather, being fully in equities, and keep adding additional capital in rising economy, is the way to be (keeping an eye on valuations ofcourse). Similarly, adding when the markets tank, and successively take float/leverage, if possible (keeping in view on markets) on way down, could be much better policy. Again, nothing is absolute gospel – a careful vigil needs to be kept throughout. But one must keep take reins of one’s financial destiny.


Oppurtunities in a Bull run

This is second most prominent question asked. The answer resides in part in the above section - i.e. managing one's allocations. Its impossible to predict the run of a bull market, or a downfall. The only way is to buy cheapest wherever possible and keep a dynamic allocation, as described above. There is no dearth of opportunities in an upwards markets too. For years, markets can remain high (or low) than one’s wildest expectations – the only way out is to develop multiple skills/earning streams and keep allocating periodically.

I was buying some company last year. This year, I'm still buying it at 3-4x original price because the valuations have moved ahead and growth has accelerated and is visible. So, anchoring to original buy price is WRONG criteria. RIGHT thing is to anchor to the moving intrinsic value and keep allocation a dynamic process.  

As they say, Investing is simple, but not easy.


Etc

Found some interesting stats from different fund managers’ way of investing. Below is a pullout from Bruce Berkowitz’s Fairholme presentation. This is to point out the concentration being followed in his fund, where top security is almost half of the fund. Similar point was recently made by Pabrai at an investing summit in Mumbai,  please enjoy the interesting conversation here.


Friday, July 11, 2014

H1 CY14 - Clear Views


In the business world, the rearview mirror is always clearer than the windshield - Warren Buffett


In hindsight, it’s clear that the pessimism of july-13 was undue and exaggerated (It looks too easy today, but it could have continued had India not got full majority). Equally true would be the clarity and hope with which many local businessmen are viewing the windshield. With the clear majority at center (government), functioning and policy making, which went in topsy-turvy in last few years, should be a low hanging fruit for the new Government. Hopes are high and with clear majority at center, the runway is clear now. 

Presently, most of the clueless retail investors, who didn’t make money since 2008, are desperately washing off their hands off the stocks! Domestic investment institutions are facing redemptions - and are biggest sellers (and losers) in the markets. Read this interesting article by another fund manager Samir Arora, on money flow into markets. The big gainers in the markets have been FIIs and HNIs, who added when the markets were down, and had been consistent buyers during last one year! With such immense optimism (read this), it is folly of common investors not to participate in the growth now! With such a clear majority, growth-oriented budget and low hanging fruits, environment cannot be more perfect for India to do well in coming years. 
  
Portfolio.
WE are staying put with larger part of the compounding portfolio. With compounding happening, growth visible and low valuations, I think we are at 50cents to a dollar value presently. We have liquidated tiny part, which was of slow moving/headwind-facing companies. Will keep this cash handy for use during short term fluctuations. In case you need to understand about specifics, please feel free to talk. 

Etc...
I was invited to deliver a talk at CFA institute - New Delhi. You may watch the video here or read the text here. 


Saturday, January 11, 2014

H2 CY13 - Rollercoaster


In General

Markets had a roller coaster ride in last half. In markets, the retail participation is dipping and equity has become unloved. Cash volumes have dipped to 6 year low. DIIs are also facing huge outflows and redemption pressure, and closures, which is making them sell in the markets every now and then.

July faced credit crunch due to US taper news /china credit crunch. Bureaucracy is still major headwind. Many PE backed companies, with assumingly better corporate insights, which went for aggressive expansions earlier, are now lining up for debt restructuring. Coal and power situation is problematic – this is a great article which shows how India’s economy and power capacity expansion got stalled due to hoarding of national coal assets. Businesses are hanging on hoping for turnaround.  

Few major good developments are - Reliance has started its much awaited expansion work recently + new gas tariff regime should see some boost in gas volumes + govt is keen to allocate 2-3 Ultra mega power projects ASAP, with additional benefits to encourage investor participation. Hopefully this will move the economic needle. There are also M&A starting to happen in infra/power sector, where indian promoters are willing to let-go of the assets to deleverage the balance sheets.   

Overall, I think the dwindling volumes and retail participants altogether ignoring the stocks, is a good sign. Athens and other PIGS were also highly unloved last year when they were assumed to exit Euro –  subsequently they have doubled up.


Portfolio

Portfolio remains same, without any major shakes. We added one major position, with great tailwinds and promoters aggressively looking to enhance value. Overall our companies are doing well, without any strains from debt overhang or capital management issues. One of these business is facing tailwinds as sales have dipped - I will write to you about the major positions in a different note.

The way to understand the financial-numbers of our portfolio companies is to see their progress in terms of (1) how much capital they can generate (2) how well they can allocate that. IF the company isnt allocating capital properly, it will hamper the businesses sooner or latter. And IF the management is building on the book well, compounding well, cannibalizing (buybacking), eventually market cap will have to match it up. The ticker is just a voting machine, sooner or latter to be rectified. The number to view is growth in networth, which Buffett mentions in his returns.  

Markets will beat one’s smartest buying and selling price and there is just no way to predict that. The trick is to monitor the health of the underlyings, and if they are performing well, ignore the markets – or rather use the markets. Buffett often applauds Henry Singleton, one of the smartest capital allocators, who effectively used the down markets to enhance shareholder value. One thing very clear from operations of Singleton/Buffett/Munger is usability of cash from market-unrelated operations, which makes them participate much better in market rides.

Im glad about people who added further capital in markets, when prices were down.  

As shipping tycoon Coco says in The Shipping Man – “When you want to cry,really u should buy! Investors only lose money when they lose patience”... I recommend reading this book to understand asset acquisition and financing.


Et al..

1) Contraction is not a loss. Contractions are part of market. Loss is permanent impairment of capital. For example – if a company has to sell good assets to salvage rest, that's impairment. Volatility isn't a loss!
2) Decisions are taken on at-present valuations basis. Selling things which may be underwater, but facing headwinds, to buy out things which are more cheaper and facing tailwinds, is emotionally painful, but a GOOD decision. Our anchor isn't the cost price, but the value in exchange.  
3) Equity isn't clockwork, it isn't like a regular monthly paychecks or a fixed deposits ringing cash register every year. Its highly erratic, and one got to be and think like a businessman to understand it. Payoffs r erratic but profitable. Jason Zweig has described it very well in Your Money and Your Brain. 


Thursday, July 11, 2013

H1 CY13 - Uncertainity & Oppurtunity


Charlie Munger:
It's in the nature of stock markets to go way down from time to time. There's no system to avoid bad markets. You can't do it unless you try to time the market, which is a seriously dumb thing to do. Conservative investing with steady savings without expecting miracles is the way to go.


STATE OF AFFAIRS
THE conditions are similar to start of previous decade. Businesses are slow, working capital is struck, and companies are facing a very uncertain environment. Many companies levered and did commit huge capex in 2010-2012 period, estimating that Indian economy needs more infra/ports/power/roads etc. However things didn't pick up as expected. Many companies have started facing degrowth.

The mood today is to keep the purse closed, and save liquidity. Till last year, many capital goods/machinery advertisements were appearing in national dailies. Presently, its no more the case. Newspapers are offering huge discounts to attract advertisements lately.

Car sales are degrowing first time in last 12 years, power plants are jostling for coal and gas and to cover cost of fuel, road companies are fighting for right of way and liquidity constraints - and incumbent bureaucracy is looking forward to the next government!


 Much of the slowdown seems to be a self-inflicted pain. Government's inability to plan, foresee and take actions led to incongruous conditions. The Govt had nearly a decade to push forward reforms like power pricing, subsidies, oil and gas, distribution and transmission reforms, coal availability reforms, land reforms, labor reforms, etc. However it decide to suck its thumb and take it easy.

Recent times have seen Govt pulling up its socks. Few reforms have been initiated like State electricity boards reforms, taking decision on passing  the international coal prices, taking decision on passage of gas prices to the customer, frequent price changes in case of petrol – which were mostly unanticipated and landmark decision.  Few others are in pipeline, like change in premium charges from the road builders, etc.  The pace is too little, too slow. The govt is also acting cautiously especially after the corruption scams which have erupted in last few months. 

As IDFC chairman mentions, policy making has to fasten up, upto the aggression of entrepreneurs. With the global problems, India could have and can still do well if govt actions are quicker.


MARKETS
The dichotomy in the Indian markets is crazy. The optimism in good quality businesses and the pessimism in businesses facing poor environment is stretched to extremes.

Other markets like US, Europe, Japs have been too benevolent in last few years –funded excessively by the central banks. A comparison of US market, and various sections of Indian businesses, show the widening gap. Here, few top companies and sectors like fmcg, consumables, etc continue to sell at 30-40x. Rest 90% of market constituting the manufacturing economy is multi year low.


We had favorable environment for past few years – monsoons were successively good, Govt had enough ammunition to boost the economy with stimulus, rural employment schemes, and loan waivers. It boosted confidence of industrial sector too, and they went in for capacity additions and expansions. Today, conditions are not very conducive  Govt is constrained with its own finances. Banks are saddled with NPAs. Macros, foreign liquidity, etc is turning unfavorable.

As liquidity is chasing only few stocks, things get turbulent with an eye blink. Domestically, Titan, Infosys, Wockhardt, IGL, etc – the much loved, admired and good quality companies – saw crashes as much as 50% in a matter of few days, with the change in environment/regulations. Internationally, actions from the Chinese central bank / Bernanke – shook India and other markets badly lately. In past fortnight,  the bond trading in India was halted to cool down the market. With the expected rise of yields in US and elsewhere, capital outflows may turn turbulent from India, unless Indian consumption story is prime-pumped soon again.  


THE CURIOUS CASE OF PSU VALUATION

The Public Sector Units are particularly hit very badly in last few months. In a bid to manage its own finances, Govt desperately sold off some public sector companies in fire-sales in the JFM quater. For Govt, managing the fiscal deficit and credit rating is more crucial than getting good price for their assets. The desperate sales have been no less than lunatic. The effect had been so bad that minority shareholders confidence is shaken.  Case in point is the largest steel maker of the country, with its own ore mines, which was sold by Govt at 63 cents to dollar book, at around 25k cr market cap, when they had already executed capex worth 50k cr, mostly from its own internal accruals! What was required to be done at good times, was done at worst. Such disinvestments in bullish markets would have fetched 5-6x current prices. It is disheartening to see the exasperation of entrepreneurs and the apathy of government. 

However, such gloom has created good opportunity. It makes sense to acquire few such public sector assets. Clearly, it would be a smart move if one can raise just a long hold PSU-fund and acquire assets here and sit on the ass for decade.


PORTFOLIO 
The composition of our portfolio is good. I am glad with the strengthening of their balance sheets, and the way they are managing in such operational environment. There are no major problem of working capital, debt, or capital structure etc – although forex volatility and general slowdown is tightening.  All eyes are on governmental reform process to lift up the business investment cycle.

The biggest risk presently is paralysis to acquire assets. Mind usually freezes in such times. This is not a time to be paralyzed over contraction of valuations. But rather acquire assets slowly for long term. It may well continue for months/years, but focus got to be kept on acquiring things which will do well when the economy turns around. Recent falling sales or profits will recover, if cash producing ability and strength of the balance sheet of the company is good! 

As Graham quotes Horace in Security Analysis - “Many shall be restored that are now fallen, and many shall fall that now are in honor”


 Few good reads - 


Thursday, January 17, 2013

H2 CY12 - Letter


So far..

Indices has moved back to Jan11 levels or closer to Jan08 levels. However, indices today are very different from previous times. The exchanges revamp the indices, by adding flavour-of-the-season and expelling the rotten tomatoes very regularly ((link link)) - (This makes indices a good hold for ultra-passive investments.) 

The rise in the markets have got less to do with drastic improvement in the biz environs. On one hand, consumables/FMCG/b2c businesses have done very well in last 2 years of slowdown. Not only their earnings have risen, their multiples are rising faster and consistently crossing their own all-time-high valuations. However I am not comfortable with such high multiple businesses, as I think even a minor negative surprise can prick the balloon. However, I may commit mistakes of omission here. 

Other side of the market - the manufacturing, auto, capital goods, metals, infra, etc, are severely affected this year. Industry capex is very poor. Power shortages and cuts are affecting industry in many states. This is also leading to industry-migrations. This end of the market is very attractively priced.  

Few positive changes have already happened in the power market. RBI and Central Government has pushed states to revise tariffs, and improve the distribution efficiency. Coal situation is poor. Wind industry is down 40% this year, due to removal of accerlatated-depreciation incentive. This year too we are looking for steep hike in power prices. Its move in the right direction, however its too early to say anything. 

Activities
As our positions are concentrated, we had minimal activity. We are adding up to our holdings.

New discoveries, readings, et al
My discovery of the year was on the topic of confabulations - the story making and value-adding ability of the mind to the reality. Neuroscientists call this the virtual-scene-simulation. Its a important topic as it bridges the connect between neuroscience-mind-spirituality-happiness. Do read. (Check these amazing cartoons) 

And readings..
Linkedin removed the amazon-book-app from its website. In absence of it, I am compiling some good reads here.. 
-Strangers to Ourselves
-Proust was a neuroscientist. 
-The Three laws of performance - Zaffron & Logan
-Power of Now - Eckhart Tolle
-The top five regrets of the dying
-Worldwide laws of life - John Templeton
-The Humble approach - John Templeton
-Education and the Significance of life - Jiddu Krishnamurti

Sunday, July 15, 2012

H1 CY12 - Bright Spots


The business conditions haven't changed much in last few months. The signs of slowdown are now visible in some sectors, and now the Govt-bodies are also conceding to it. Biggies of the corporate sector have made multiple pleas to the Govt to push the reforms. Hopefully things will move.

Human minds works with a negative bias. The default mode of mind is to ignore the good things, and accentuate the bad things. This worked well in hunter-gather environment - but now, this trait is wired into our brains forever. Even without any external threat, mind makes its stories and produces unnecessary anxieties. Rick Hanson (Buddha's Brain) tells this as being in unnecessary flight/fight mode and unhealthy for our body.

Looking at the brighter side is equally important trait, which leads us towards development, growth, and entrepreneurship. Dr Martin Seligman – the positive psychology, and learned-optimism pioneer – says that we usually forget that nothing in this universe is permanent or prevailing condition. Things change for good. And its important to keep a tab on such changing and uplifting scenarios.

In past few months, few sectors have shown good movements.
• Power – Govt is trying to do its bit, and industry is not letting off Govt. Power prices in most of the states were increased last yr, and are again looking to be hiked this year. A recent Crisil report suggests that there is a big lag between rise in income levels and real power prices – i.e. consumers are willing to pay higher prices to get regular supply of power. Moreover, fall in coal prices internationally is good for Indian power producers.
• Cement production and prices are up in last few months, despite slowdown reports on infrastructure front.
• Consumables are doing well.
• NBFCs, catering to home-loans and auto finance are showing good growth.
• Overall, India, even within BRIC, isn't looking as bad as reported – Read this

(((Do you see any more? Send me the bright shoots which you can find around.)))

Markets are reasonably priced – in last several months, many things have gone from reasonably priced towards higher valuations. We are adding to our old positions, and are allocated comfortably.

Landmark

I attended this course recently - usually referred to as 'The Forum' globally – It was started in US in 90s. Its either loved or hated, due to its structuring and flow. The coaches rip apart the blind-spots and past foundations of the participants, and helps one see the past baggages, which aren't any good for creating the future which one desires. I recommend this, if it is available in your country – go and check it out.

Tuesday, January 10, 2012

H2 CY11 - Déjà vu


The fall in the market feels like 2008 - its ‘everyday low prices’ time again.

2011

The year went well - markets fell and “Sanborn” grew.

Our “Sanborn” - the fertilizer company, containing nearly quater of our assets, did very well. The thesis worked out quite fast - just over last 2 years. I expected it to add up cash profits of around 50-60 Rs/share on our cost of around Rs 200/share (which was nearly the investment/cash value of the company, thus protecting the downside risks).

The chemical compound which they make - shot up rapidly in 2010-2011 period and company reaped something like 100 bucks of cash profit per share per year!

Our cash position was large at the beginning of the year - Additional windfall came from liquidation of "sanborn", which further added to liqiuidity in the falling markets.


Agri Company
I invested into a company facing a rumoured loss and a liquidity crunch. It was a market-loved company with marquee PE funds as major investors + a reputed CA firm.

They are agri-traders and some agri-trades went haywire for them. The promotors had overleveraged their personal balance sheet, by pledging their personal stakes. With fall in stock, lenders became jittery, and in rush to get out of the stock at any price, further depressed the prices to a lucrative levels. I invested into it as price was quarter of book, company had liquidity problem which they were working on, the hard assets were good, and stock had sellers overhang. The upside expected was much higher than the downside risks.

However, with the fall in markets in Oct-nov period, good compounders had become more lucrative + company couldnt raise liquidity as mentioned by the management + business deteriorated as import of raw material became expensive & industry margins were squeezed + company started making delays in salary payment + there were reports of employees jumping off the ship.

Considering all this, I decided to exit the trade and switch over to somethings else.


Present condition

There is lot of uncertainty regarding future projects in the country - large capex is slow/stalled. But still the country is expected to grow at 6-7%, and within that some companies will do 20%+. Business conditions arnt as bad as perceptions - read Kamath interviews here and here and here(one of the better people to track).

We are comfortably positioned in the makets, holding back some 20-25% as cash. Our companies are facing general sectoral headwinds, with a few facing temporary-solvable-distress situations - hence low equity prices. Many have fallen close to all time low levels.

Our job is to find the right company and pay the RIGHT price. This time, unlike 2008, good companies, doing well, havnt fallen to good prices. There is no liquidity driven crises like 2008 - yet. The general disenchantment about the government’s pace of action may lead to a slow grind for the equity prices for year or two. I hope our cash holdings will give a good opportunity to buy more as markets fall down. Net net, i consider the present fall as once in a decade opportunity, coming up for the second time :) and we are happy to see "everyday low prices".


John Malone / Mohnish Pabrai / Chuck Feeney
Mohnish Pabrai visited Prof Bakshi’s classes at MDI Gurgaon recently. It was enlightening to talk to him and interesting to know how he is thinking about his allocation strategy over past few years.

I found another interesting person in “Cable Cowboy” - John Malone. Malone came up as a “disguised” fund manager, operating in media/cable industry. He used all the financial alchemy (dual voting stocks, stock swaps, zero tax structures, hiding earnings under high depreciation, leverage, etc) to create massive shareholders value over 3 decades. Recommended read.

The best find of the year was existence of a unknown guy named CHUCK FEENEY. He was the owner of Duty Free Shops and made business from zilch to multi billion dollar value. But thats just a small part. The best part - he kept his hedonism low and gave away his wealth - everything - for education and medicine. A real gem to emulate. Do read him in his bio.

One common thread which comes across most of such guys is - they are all extraordinarily long term thinkers, not paying attention to short term profits, running ulta-frugal operations, not wasting anything, concerned about building assets, and operating in taxfree structures. Conventional wisdom doesnt understand this - but as Buffett said, conventional wisdom is more on conventions than on wisdom.